Reduce the upfront hurdle
Eligible buyers may receive up to 20% of the purchase price or appraised value toward down payment or closing costs, capped at $150,000.

California Dream For All · In & Around Sacramento
Dream For All can help eligible first-generation homebuyers bridge the down payment gap through a shared appreciation loan. We will help you understand the opportunity and what to do while the application portal is closed.
No pressure. Clear answers from local real estate professionals.
Tell us where you are in the process. We will help you understand the program and your realistic next steps.
Your information is private and will only be used to respond to your request.
CalHFA closed new applications on March 16 and released voucher decisions in May. If you applied, check your official portal account. If you did not apply or were not selected, this is the time to understand your eligibility, strengthen your finances, and compare other assistance programs.
View the official CalHFA status ↗Because it allows you to buy a home with $0 down and qualify for more since California is doing 20% down on your behalf!.
Eligible buyers may receive up to 20% of the purchase price or appraised value toward down payment or closing costs, capped at $150,000.
A larger down payment can reduce the amount financed and may create a more manageable monthly housing payment.
Reaching a 20% down payment may eliminate private mortgage insurance, depending on the final loan structure and approval.
The starting checklist
These are the major program gates. Final eligibility and loan approval are determined by CalHFA and an approved lender.
Walk through my situation →All borrowers must meet CalHFA’s first-time homebuyer requirement.
At least one borrower must meet CalHFA’s first-generation homebuyer definition.
At least one borrower must be a current California resident.
Combined household income must fall within the Dream For All limit for the county of purchase.
Applicants work with a CalHFA approved lender and obtain the required pre-approval.
CalHFA required homebuyer education and Dream For All education must be completed.
How a future round may work
Review income, credit, funds, monthly payment and obtain the required CalHFA lender pre-approval.
Submit the required application and documents during CalHFA’s announced registration period.
Applications are selected through a randomized process and supporting documents are audited.
Selected buyers receive a limited period (90 days in the 2026 round) to shop for and secure a home.
Understand the tradeoff
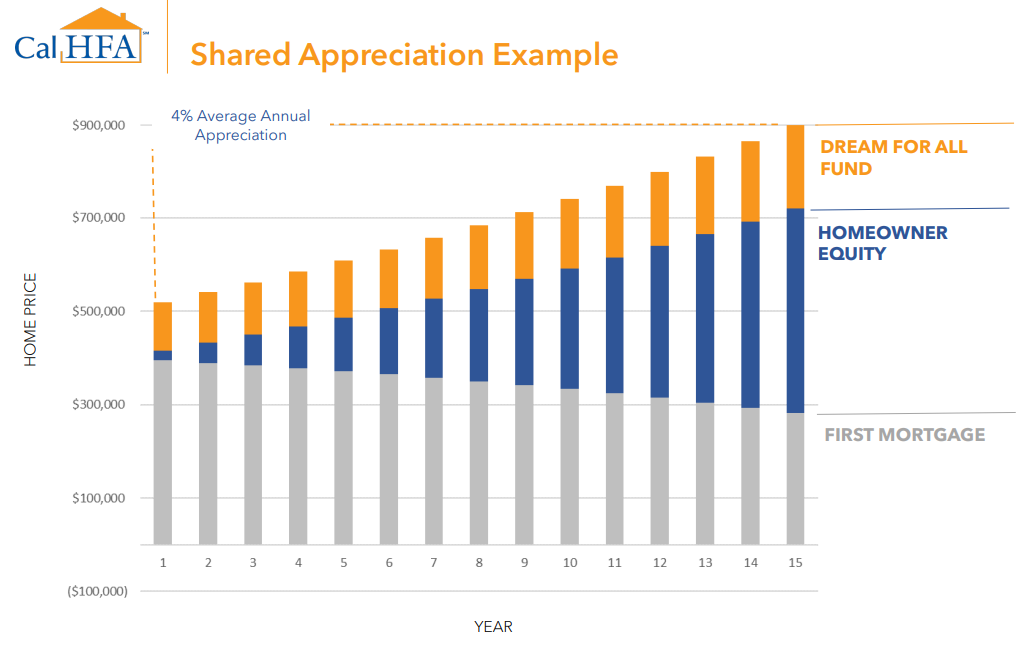
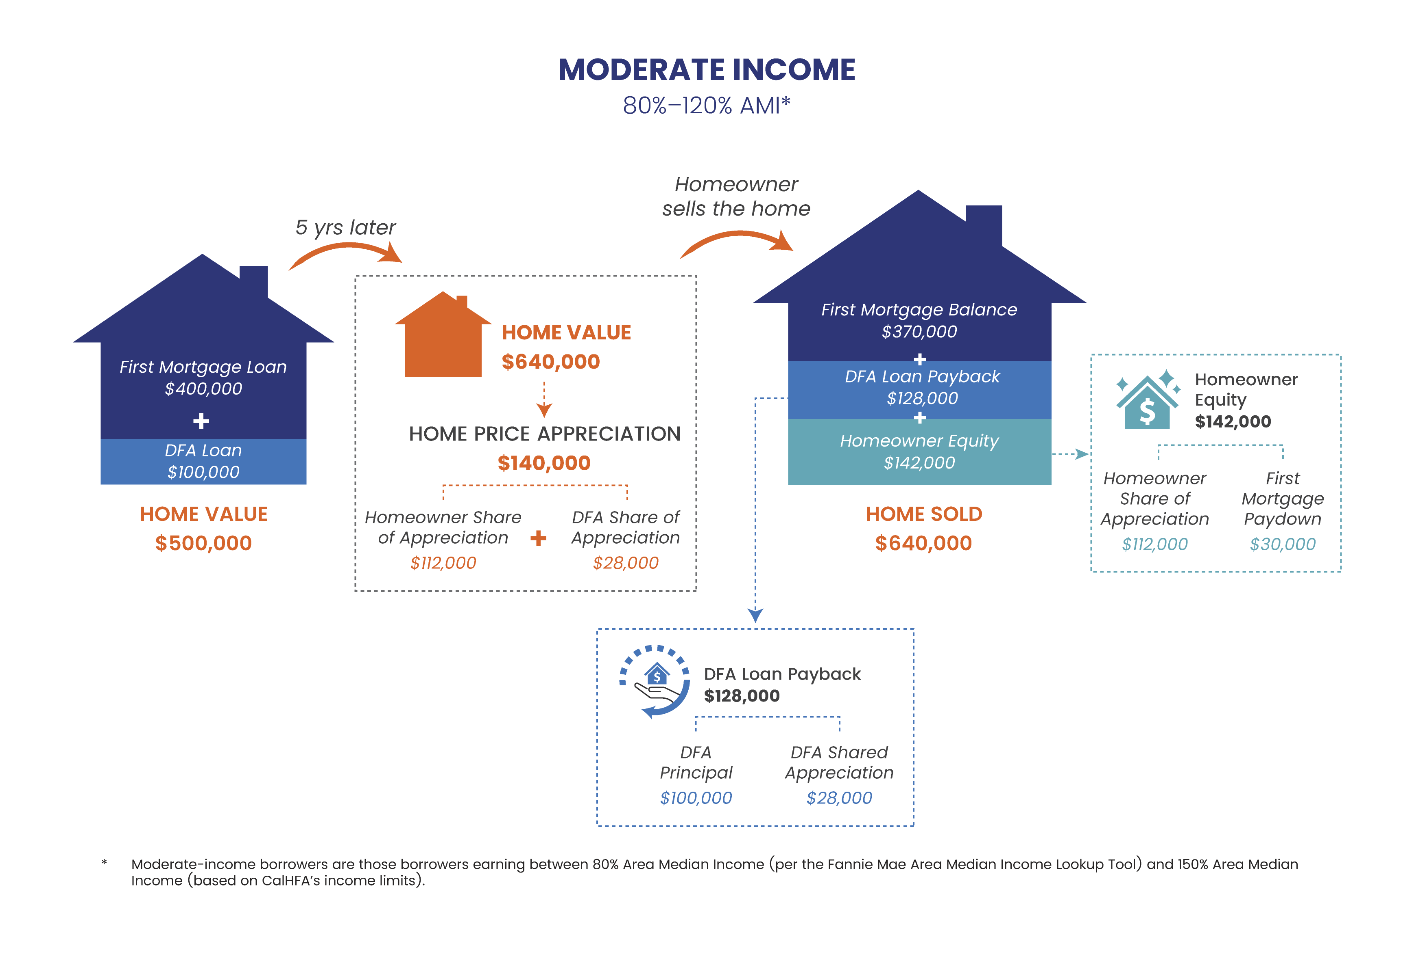
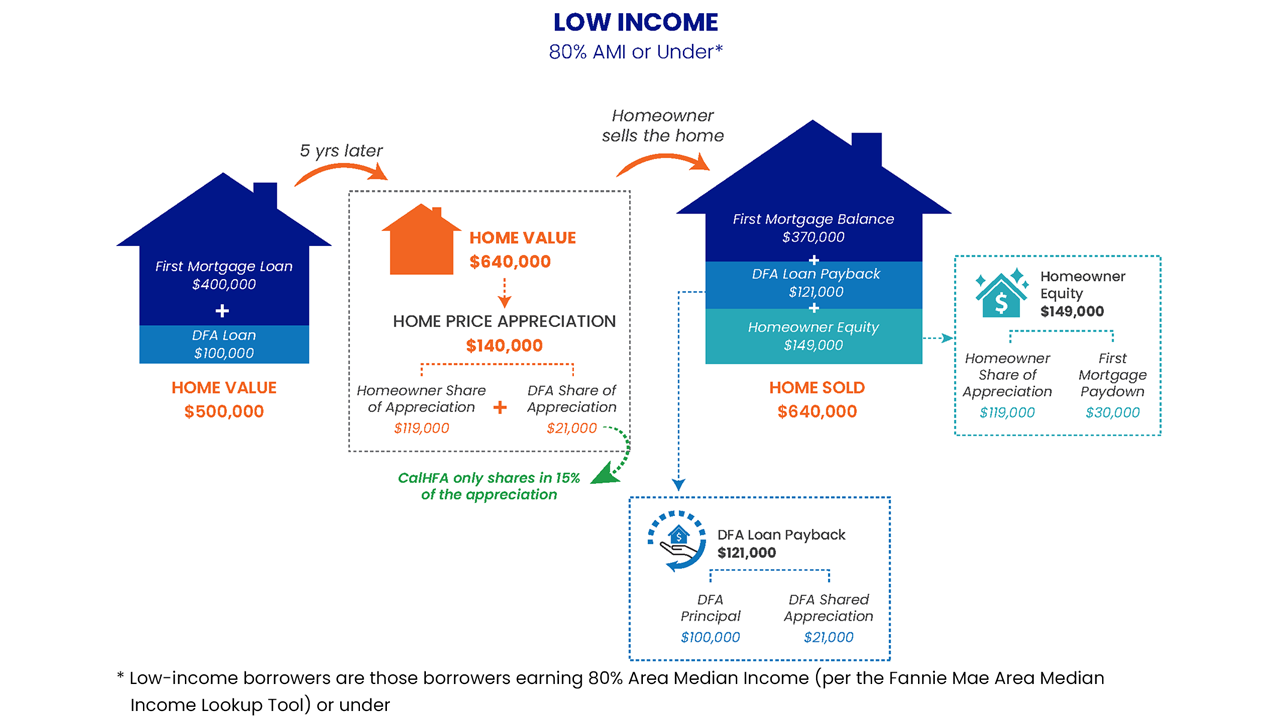
Dream For All is a shared appreciation loan, not a grant. The state helps with your purchase today. Later, after a triggering event such as selling or refinancing, you repay the original assistance plus the share of appreciation defined in your loan documents.
See the numbers visually
These CalHFA examples show how the original assistance, mortgage paydown, appreciation, and homeowner equity can work together over time.
The Homeology difference
We help you look beyond the headline and understand the payment, timing, home search, tradeoffs and backup options so you are ready to act without feeling rushed.
Clear answers
No. CalHFA closed the 2026 application portal on March 16, 2026. Applicants from that round should check the official voucher portal for their status. You can still prepare for future opportunities and explore other assistance programs.
No. It is a shared appreciation loan. The original assistance and an agreed share of the home’s appreciation becomes repayable after certain events such as a sale, transfer, or refinance, subject to the final loan documents.
CalHFA uses a specific definition involving the borrower’s prior homeownership and, in many cases, their parents’ current or past homeownership. A CalHFA approved lender should verify this requirement for your situation.
No. The recent rounds used a registration period followed by a randomized selection and document audit. Submitting early within an open window did not improve an applicant’s odds.
You may still have other paths. CalHFA recommends speaking with an approved lender about other assistance options and Homeology can help you compare those programs with conventional low down payment strategies.
We guide buyers throughout Greater Sacramento and surrounding Northern California communities, including Sacramento, Placer, El Dorado, Yolo, Sutter, Yuba, and San Joaquin counties.
Your next step is simple
Tell us where you stand today and we will help you map out the next move.
Homeology Real Estate is not CalHFA and is not acting as a lender on this page. Program availability, eligibility, income limits, assistance, repayment, appreciation sharing, timelines, rates, fees, and requirements are controlled by CalHFA and participating lenders and may change. Information is general and does not constitute a loan approval, commitment, tax advice, or guarantee of funds. Equal Housing Opportunity.

DRE # 01966803 | 01801668
Homeology Real Estate ©
All Rights Reserved
